Four | Buy Now, Pay Later
Four Technologies, IncShoppingVerified
- 4.75K Reviews
- 4.6
- Downloads
- 1,000,000+
- Price
- Free
Screenshots
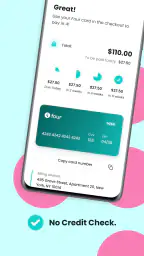
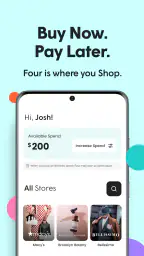
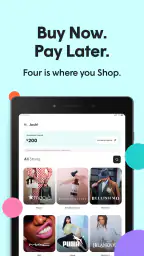
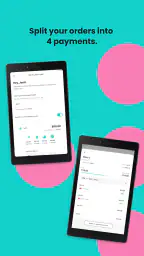
 Analysis by Appwesome
I approach buy-now-pay-later apps as payment tools, not as extra spending money. That distinction matters with Four: splitting a purchase can make a planned expense easier to manage, but it does not make the item cheaper or the household budget larger. I’d consider it when I already know what I need, can cover the scheduled payments, and want to spread the timing of that cost. If I’m shopping because a payment option makes an impulse purchase feel affordable, I’d step back instead.
Choosing a payment method that suits the purchase
When I’m deciding how to pay for an online purchase, I start by looking beyond the amount due today: the full total, the timing of later payments, and what else my budget must cover. That makes it easier to see whether Four is genuinely convenient or whether paying in full—or waiting—would leave me with fewer commitments. I’d use that comparison to judge the purchase first, then choose the payment method that fits it.
Start with the budget, not the checkout button
Before choosing a pay-later option, I’d check the full purchase total against upcoming bills and other commitments. A useful habit is to write down the purchase, its payment dates, and the money already allocated to essentials. That gives me a clearer answer than asking whether the first payment looks manageable. It also makes it easier to decide whether paying in full, waiting, or splitting the cost is the better fit.
This is where Four can be useful: it is a shopping app from Four Technologies, Inc, built around paying for online purchases over time. Its appeal is straightforward, rather than a broad set of money-management tools. I would treat it as one way to complete a planned checkout, not as a budgeting app or a reason to stretch a budget beyond its limits.
A practical way to test whether it fits
For a purchase I’m considering, I’d compare the total cost and payment schedule with my normal card or other payment choices before placing the order. I’d also make sure I understand which payment method will be charged and when, then leave enough room in my account for those dates. This quick check is especially useful if several purchases are already being paid off: each one may feel small in isolation, while the combined schedule can be harder to manage.
There is a simple question I’d ask myself: if I had to pay the entire amount today, would I still choose this item? If the honest answer is no because the purchase is not important or affordable, splitting it does not solve the underlying problem. If I would buy it anyway and the timing is the main issue, a payment plan can be a reasonable option—provided I can keep track of the installments.
Where Four is most useful
I see the strongest case for Four when an online purchase is already planned and paying the full amount at once would be awkward, even though the purchase is within reach over time. Think of replacing a necessary item or buying something for a specific occasion: the payment split may help line up the cost with a budget that has room across several paydays. I would still compare the total and terms at checkout rather than assume every order works the same way.
Other Stories to Read
It may also suit someone who prefers a dedicated checkout choice instead of putting every purchase on a revolving credit balance. Those approaches are not interchangeable: a pay-later plan has its own schedule, while a credit card has its own billing cycle and terms. I would pick the option I can understand and repay reliably, not the one that makes the purchase look easiest in the moment.
Four is free to download, has an Everyone age rating, and is listed with a 4.6 average from around 11,000 ratings. It has over 1 million installs, and its current version is 1.17.56; the app was released on January 22, 2021. Those details suggest that it has a substantial audience, but popularity does not tell me whether a particular payment plan fits my finances. I’d still read the checkout terms for the order I’m making.
When another route makes more sense
If I have the cash available and paying now will not interfere with bills or savings goals, paying in full is usually simpler: there is no installment calendar to remember. If I need longer to repay, I would compare suitable credit options carefully rather than assume a short pay-later plan is designed for that situation. And if I’m unsure whether I can meet the scheduled payments, I’d postpone the purchase or choose a less expensive alternative.
There is also a difference between a shopping payment app and a store’s own financing offer. A store-specific option may be convenient for a particular retailer, while an app-based checkout method can be useful when it appears as an option at participating online stores. I would not assume that a payment method will be available everywhere; I’d check the actual checkout page for the shop and item I want before building a plan around it.
The right comparison is not simply “which option has the smallest payment today?” I’d look at the full amount due, payment timing, and what happens if my plans change. For a return, cancellation, or order adjustment, I’d check how the retailer and payment provider handle the transaction before relying on a particular outcome. That small bit of attention can prevent confusion later, especially when a purchase is split across several payments.
Keeping a payment plan manageable
A concrete example: I’m shopping online for a coat before a cold-weather trip. Rather than add it to my cart and decide at the last second, I’d confirm that the coat is genuinely needed, check the full price, and make sure the scheduled payments fit around rent, groceries, and travel costs. If I use Four, I’d record the due dates alongside my other bills and keep the confirmation somewhere easy to find. That turns the plan into a known commitment instead of a surprise debit.
A less obvious but useful habit is to wait until I’ve reviewed the whole cart before choosing how to pay. Adding small extras after deciding that the first item’s installments look affordable can quietly change the total commitment. I’d also avoid starting several plans close together unless I’ve written down their combined dates and amounts. The point is not to make shopping complicated; it is to make the full obligation visible before I agree to it.
Reminders can help, but I would not rely on them as my only tracking method. I’d keep the payment schedule in a calendar or budget as well, particularly if I already have recurring bills or other installment commitments. If an expected reminder does not arrive, a personal record still gives me a way to check what I owe and when. This is a small step, but it makes a short-term payment plan less likely to disappear from view.
What to expect from the app itself
Four is a free shopping app with a focused purpose, rather than a general-purpose marketplace. That makes the key question practical: does the checkout for the item I want offer Four, and do the terms shown there suit me? I’d install it only if I expect to use that payment route, then check the app and the retailer’s checkout for the information relevant to my purchase. The app’s presence on a phone does not guarantee that every store, order, or item will be eligible.
Compatibility is another straightforward check. The listed minimum operating system is Android 6.0, so I’d confirm that my device meets the requirement before trying to install it. The app’s listed version is 1.17.56, but version details alone do not tell me how a particular purchase will be approved or handled. I would make the decision based on the live checkout information, not on assumptions drawn from the app’s general premise.
For someone who asks whether they can use it for every online purchase, my answer is to check the specific retailer’s checkout rather than count on universal acceptance. If they ask whether a payment split makes an expensive item affordable, I’d say it changes the timing, not the underlying cost. And if they wonder whether it is better than a card, I’d compare the actual terms and repayment dates for their situation; a familiar card may be simpler for one person, while a defined installment schedule may be easier for another.
My recommendation
Four is worth considering if I shop online, have a clear purchase in mind, and can comfortably meet the payments shown before checkout. The app has a 4.6 average across around 11,000 ratings, and its free download lowers the barrier to trying it, but neither fact replaces a personal affordability check. Its best role is as a convenient way to handle a planned purchase—not as a shortcut around deciding whether I should buy it.
I would skip it for an impulse buy, for a purchase that already strains my budget, or when I need a longer repayment window than the checkout offers. I’d also choose another method when paying in full is easy and I want to avoid tracking installments. Used with a clear limit and a written note of the dates, Four can be a practical option; used to justify spending beyond that limit, it is the wrong tool.
Hey there! So, I’ve been diving deep into the world of buy now, pay later apps, and I stumbled upon something interesting—Four. This app promises to make your shopping experience smoother and a lot more flexible. Let me walk you through what I found out after giving it a spin.
First Impressions and Getting Started
Right off the bat, setting up Four was a breeze. The design is super user-friendly, which made the whole process feel like a walk in the park. All I had to do was download the app from my app store, sign up with my details, and boom, I was in. They even have this neat little guide that walks you through how to use the app. For someone like me who’s always in a rush, this was a huge plus.
How Four Works
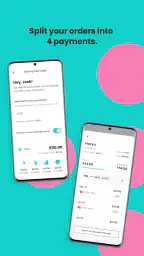
So, here’s the deal. You find something you want to buy, maybe it’s that snazzy jacket you’ve been eyeing, and instead of paying all at once, Four lets you split the cost into four interest-free payments. This is particularly handy if you’re trying to keep an eye on your budget. What I love is that there are no hidden fees, which is a rare find these days. It’s pretty straightforward—what you see is what you get.
The Shopping Experience
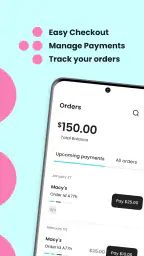
Shopping with Four feels like having a financial buddy who’s got your back. I tried it out at a couple of online stores, and the integration was seamless. I didn’t have to jump through any hoops to get it working. Just choose Four at checkout, and you’re good to go. The app sends reminders about upcoming payments, which is quite handy if you’re like me and forgetful at times.
Features That Stand Out
- Interest-Free Payments: The fact that Four doesn’t charge interest is a game-changer.
- Easy Setup and Use: From downloading to shopping, everything is smooth sailing.
- Payment Reminders: Keeping track of payments is made easy with timely reminders.
- Wide Range of Stores: It works with tons of online stores, so you're not limited in your choices.
Is It Really Worth It?
Honestly, if you’re someone who likes to shop online but wants to manage spending more effectively, Four is definitely worth checking out. It’s especially useful for those big-ticket items that you’d rather not pay for in one go. The app is designed to help you buy what you need without breaking the bank, all while keeping things transparent and simple.
Final Thoughts
Wrapping it up, I’d say Four is a pretty solid app for anyone looking to take control of their spending while still indulging in some retail therapy. It’s straightforward, user-friendly, and just makes the whole shopping experience a bit more enjoyable. If you’re curious and want to give it a try, you can find it easily on your app store. Happy shopping!
Highlights
- Flexible payment plans for budgeting
- No interest if paid on time
- Seamless integration with retailers
- User-friendly interface and design
- Quick approval process for users
Limitations
- Late fees can be steep
- Limited payment options
- Requires good credit history
- Not available in all regions
- Privacy concerns with data sharing
Frequently Asked Questions
01What is the main purpose of the Four app?
Four is a 'Buy Now, Pay Later' app designed to offer users flexible payment options on purchases. The app allows users to split their purchases into four equal installments, paid over a specified period. This can help manage finances better by spreading the cost without incurring interest, provided payments are made on time.
02Is there any interest or hidden fees associated with using Four?
One of the key benefits of using Four is that it doesn't charge interest on the installment payments. However, it's important to note that late fees may apply if you miss a payment deadline. Users should always check for any potential fees associated with transactions and ensure timely payments to avoid extra charges.
03How secure is the Four app in handling personal and financial information?
Four prioritizes user security by employing advanced encryption technologies to protect personal and financial data. The app is designed to comply with industry standards for security and privacy. Users should ensure their app is updated regularly to benefit from the latest security enhancements and report any suspicious activity immediately.
04Is Four available for both Android and iOS devices?
Yes, Four is available for download on both Android and iOS platforms. Users can find the app on the Google Play Store for Android devices and the Apple App Store for iOS devices. Always ensure you download the app from official sources to avoid security risks associated with unofficial downloads.
05Can I use Four for online and in-store purchases?
Four can be used for both online and in-store purchases, depending on the retailer's acceptance of the payment method. Users should confirm with the retailer if Four is accepted as a payment option before proceeding with their purchase. This flexibility makes Four a versatile option for various shopping experiences.


